
What will happen on the real estate market in 2027 in Montpellier?
Local marketBy Antoine Dematté·October 9, 2026·Reading time: 10 min
In Montpellier, waiting until 2027 will not be enough to sell a property listed at too high a price.We defend a simple position: when an overvaluation is established, it is better to correct it than to rely on a recovery to catch up. The city's attractiveness supports demand, but buyers must always be able to finance the asking price.
We are anticipating a selective market in 2027, with significant disparities between properties and sellers. A well-positioned property can find a buyer. An excessive price, poorly estimated repairs, or fragile financing can prolong the waiting period.
For buyers, the reasoning has its counterpart: waiting for a price decline can be costly if, in the meantime, interest rates rise. It is this double trade-off that will guide our reading of 2027, without claiming to predict in advance the price of each property.
Analysis stopped on October 8, 2026. The dates of the statistics are specified: some describe transactions prior to 2026.
What figures truly describe the Montpellier real estate market?
The available data shows a price adjustment, without allowing us to announce a general decline in 2027. For deeds signed between July 2024 and June 2025, notaries in Hérault recorded in Montpellier a median price of €3,260/m² for older apartments, down 1.6% year-on-year. The median price of older houses reached €365,600, with an annual decline of 5%. These figures describe sales completed and the composition of properties sold. They do not constitute an individual estimate.Notaries of Hérault, October 2025 bulletin
More recently, the SeLoger barometer of September 1st, 2026 estimated apartments at €3,415/m² and houses at €3,978/m². It indicated respectively −2.2% and −4% year-over-year, with an average time to sale of 88 days, compared to 77 days a year earlier. These are estimates derived from another tool, not a new series of notarial deeds.SeLoger, September 18, 2026
Directly comparing €3260/m² and €3415/m² to conclude a price increase would be misleading: the time periods, methods, and properties observed differ. A serious valuation is built from comparable sales, with their dates and characteristics. The floor level, outdoor space, condition, or fees may explain a difference that Montpellier's average completely obscures. Buyer reactions then serve to verify whether the asking price is consistent.
Why Credit Can Weigh More Than Price Declines
The purchase budget depends on the asking price and financing costs. In August 2026, the Banque de France measured an average rate of 3.32% for new mortgage loans excluding refinancing. It had increased by 24 basis points since the beginning of the year. This national average covers all loan terms: it is neither a twenty-five-year offer nor an APR. It excludes fees and insurance.Bank of France, publication of October 6, 2026
An increase in the interest rate reduces the capital accessible at a constant monthly payment. A decrease in price can then be partially absorbed by financing. The buyer has not necessarily gained purchasing power. For 2027, we therefore do not rely on any promise of cheaper credit. The right approach is to start with financing that has been genuinely studied, then determine the price compatible with this budget. Simultaneously expecting both a sharp price decline and a decline in interest rates amounts to combining two assumptions.
A numerical example with constant monthly payment
We have calculated the borrowable capital for a monthly payment of€1,200 for twenty-five years, according to three hypothetical fixed rates.
Rate used in the simulation | Approximate Borrowing Capacity |
|---|---|
3% | €253,052 |
3.32% | €244,388 |
4% | €227,343 |
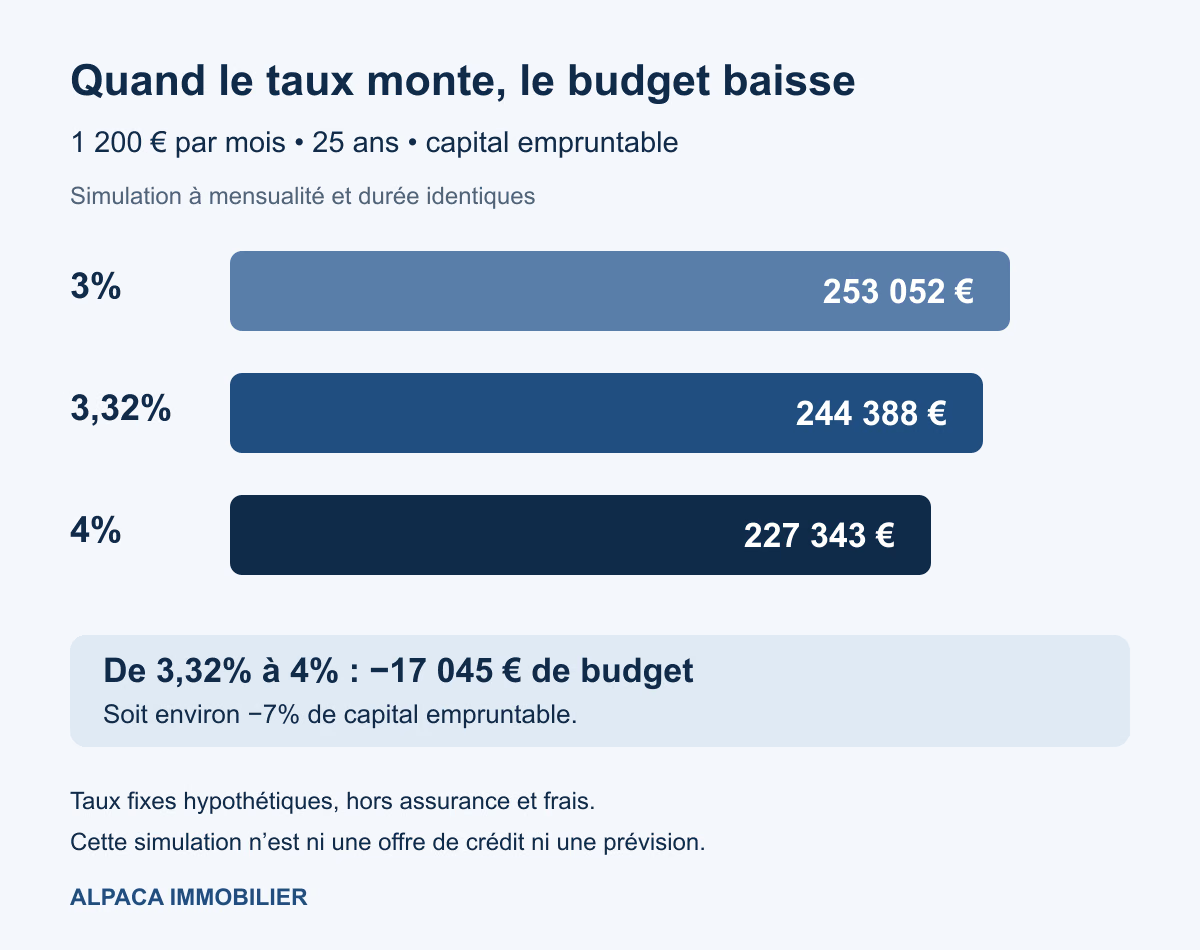
At identical monthly payment and duration, a hypothetical rate increase from 3.32% to 4% reduces the borrowable capital by €17,045. Simulation excluding insurance and fees, with no forecasting value.
Original calculation with 300 monthly installments, excluding insurance and fees. The rate of 3.32% is used as a hypothesis; national statistics guarantee no offer on this term.
At 4%, the accessible capital decreases by approximately€17,045I'd be happy to help translate from French to English, but the text you've provided appears to be incomplete. It only contains: ", soit" This fragment translates to ", that is" or ", namely" in English, but without the full context, I cannot provide a complete and accurate translation. Could you please provide the complete text you'd like me to translate?6.97%, compared to the 3.32% scenario. The move to 4% remains an assumption. But the calculation exposes the risk of waiting: a reduction in the asking price can be absorbed by a loss of borrowing capacity. For the seller, this also means that a buyer interested today will not necessarily have the same budget a few months later.
Will Montpellier's Attractiveness Protect Prices?
Montpellier maintains measurable demographic momentum. The municipal population reached 310,240 inhabitants in 2023, compared to 285,121 in 2017. The difference represents 25,119 additional inhabitants over six years, calculated from published figures. These figures describe the past population, not that of 2026 or 2027.INSEE, reference populations 2023
This growth supports housing needs. It does not mean that every new resident wishes to buy, has a down payment, or can finance the listed price. The INSEE municipal file indicates that 67.1% of primary residences were occupied by tenants in 2023, including the social housing stock. The median standard of living was €21,440 annually. This latter indicator is disposable income per consumption unit, not a salary that can be used directly in a credit calculation.INSEE, complete file for Montpellier
Population growth therefore does not automatically translate into an increase in property prices. A student is looking for a rental; a first-time buyer must gather a down payment and obtain a mortgage. For a property owner, the analysis becomes more useful when it identifies buyers capable of financing their property, in its current condition, at the asking price.
Three scenarios for the real estate market in 2027
Our central scenario for 2027 is a still-selective market. Properly valued properties could find buyers, while overpriced or complex assets would remain more heavily negotiated. Two credit developments could alter this outlook: more accessible financing would broaden demand; more expensive financing would tighten budgets. We assign neither probability nor percentage price variation to these scenarios.
The number of transactions may well pick up again without all prices rising. On a national scale, notaries recorded 949,000 sales of existing homes over a twelve-month period ending May 2026, up 5.7%. However, existing property prices increased by only 0.2% year-on-year in the first quarter. These national results do not constitute a forecast for Montpellier.# Notaries of France, First Quarter 2026 Trends
Scenario | Conditions envisaged (or "Proposed conditions" / "Contemplated conditions" depending on context) | Practical consequence |
|---|---|---|
Selective Market | Financing without major improvement | Position the price precisely and document the work |
# More Favorable Uptake | More accessible credit and strengthened confidence | More potential buyers, without automatic increase of each property |
Extended Adjustment | More expensive financing or tighter budgets | Enhanced Negotiation and Reassessment of Excessive Prices |
Sellers: Why adjust an excessive price right now?
The desired price, the amounts spent on work, and an old appraisal are not enough to determine current value. The buyer compares your property to what they can acquire with their budget. If the alternatives are more convincing, waiting until 2027 will not correct this gap.
A price reduction must, however, be based on a diagnosis. Poor ad visibility, an incomplete file, or insufficient distribution can explain the lack of viewings. When viewings are numerous but result in no offers, the price and recurring objections warrant closer examination. We recommend verifying these points before modifying the listed amount.
Waiting also has a cost: charges, taxes, potential interest, and maintenance continue depending on the owner's situation. This cost must be compared to the expected gain. Displaying a higher price for several months does not necessarily improve the final amount retained. Duration is as much part of the calculation as the signed price.
# Calculate the Wait Before Refusing an Offer
Hypothetical example:€450 per monthof conservation expenses represent€2,700over six months. Capital repayment is excluded: it rebuilds the assets.
This calculation does not justify an automatic discount. It provides a basis for comparing two options: accepting a financeable offer today or waiting for a higher offer, which remains uncertain.
The expected net proceeds and the desired sale date make it possible to decide what this expectation is worth to you. A credit to settle or a subsequent purchase may alter your decision; they do not change the value of the property in the buyer's eyes.
Buyers: Should you buy in Montpellier or wait until 2027?
Buying can be sound when the property meets a lasting need, its price is justified, and the financing leaves a safety margin. Waiting may be preferable if the project remains uncertain, if the down payment is insufficient, or if the work exceeds available means. We do not recommend a decision based solely on the hope of buying at the market's lowest point.
The complete budget must include the price, acquisition costs, mortgage insurance, maintenance fees, and foreseeable expenses. In a condominium, general assembly minutes and announced work deserve as much attention as the décor. A discount obtained at purchase can disappear in the face of forgotten renovation work.
To negotiate, we prioritize verifiable elements: comparable sales, quotes and property characteristics. An explained offer, accompanied by studied financing, provides the seller with a more solid basis for discussion than a general prediction of price decline.
The holding period also matters. A property in which you plan to live for several years calls for a different decision than a purchase intended to be resold quickly. The budget must retain a margin for additional expenses: a price reduction does not make an already heavy monthly payment sustainable.
The character of an older property does not dispense with examining its condition and the work to be anticipated.
Investors: check the rent, the EPC and the work
Rental demand alone is not sufficient to guarantee good profitability. The local observatory noted in 2025 a median rent of €13.7/m² excluding charges for vacant residential units. Its scope covers Montpellier Méditerranée Métropole and five additional municipalities. This median of observed rents does not constitute the predictable rent for a specific apartment.Rental Market Observatory, April 2026 publication
The energy schedule must also be included in the budget. In mainland France, properties classified as F will be subject to rental exclusion starting in 2028, according to the terms applicable to leases. The sale of an F-classified property remains possible.Public Service, DPE Rules
Finally, the rental framework applicable in 2027 will need to be verified. The official information consulted describes a Montpellier experiment running until November 2026. We do not presume its continuation.Public Service, supervision in Montpellier
The new DPE calculation requires an individual verification
# Translation From January 1st, 2027, the electricity conversion coefficient will change from1.9 to 1.7Some electric homes will be able to improve their rating. A certificate may update a valid EPC, without a new visit and without extending its validity.Public Service, reform announced in September 2026
This change does not renovate the property and does not physically reduce its consumption. Before negotiating an energy discount, it will be necessary to verify the updated label and the work that is actually necessary.
# Frequently Asked Questions About 2027
Will prices necessarily fall in 2027?
No. The available data does not allow us to assert a certain decline for all residential properties in Montpellier. We anticipate above all a selection based on price, characteristics, and financing.
Would a rate cut immediately push prices up?
It could support budgets. Its effect would also depend on confidence, supply, and sellers' choices. This mechanism guarantees no immediate increase.
Will an electric housing classified F automatically become rentable after the reform?
No. You must verify the individual result of the updated DPE and the other criteria applicable to the property. Modifying a coefficient does not guarantee a new rating.
For your sale in Montpellier,an estimate at Alpaca Immobilierallows you to compare your price against the property's characteristics, comparable references, and buyers' budgets. You then have a basis for deciding whether you can wait or if an adjustment is preferable today.
Go further
Have a property project?
Our experts guide you from A to Z, from estimate to signing.
Estimate my propertyor call us on 09 70 70 31 07
Prefer a call back?
Leave your number: an Alpaca Immobilier adviser will call you back quickly.
Similar articles

